Financial Advisor

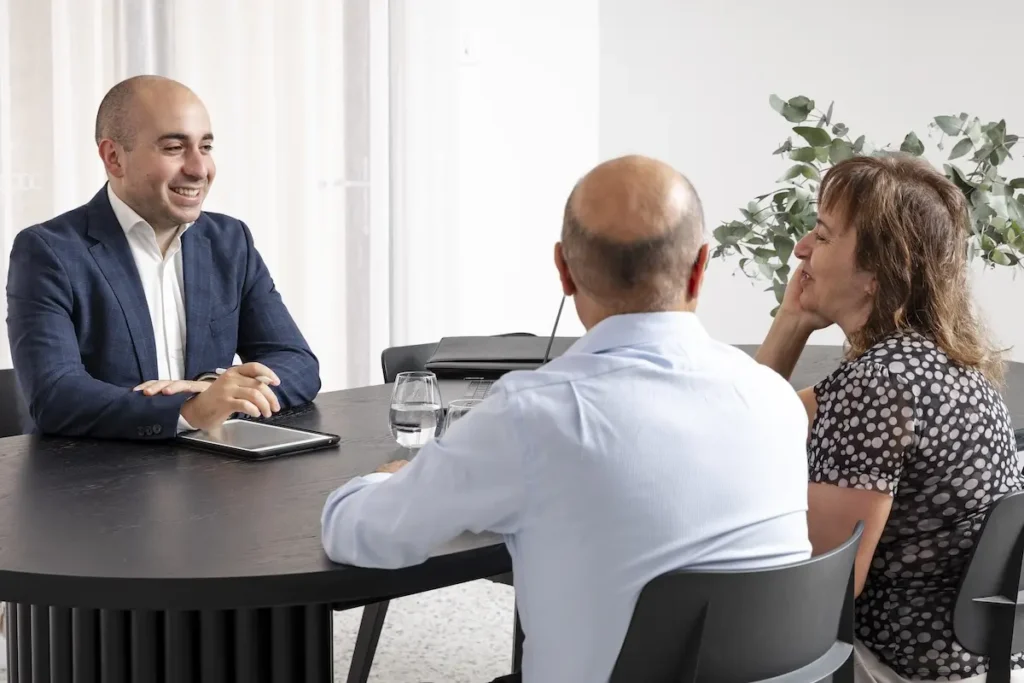
What a First Meeting With a Financial Advisor in Mentone Covers

It also sets expectations around fees, advice scope, and next steps, so they can decide if the adviser is the right fit.

What is the main purpose of a first meeting?

The goal is to confirm what they want help with and whether the adviser can assist. A first meeting with a financial advisor Mentone is typically a discovery session, designed to map priorities and identify the biggest decisions ahead.

They should walk out knowing what the advice process looks like, what information is needed, and what the likely timeline is.

What should they bring to the appointment?

They do not need perfect paperwork, but a few basics speed things up. For a first meeting with a financial advisor in Mentone, it helps to bring recent payslips, super statements, a list of debts, and a rough monthly budget.

If they have insurance through super, investment accounts, or a mortgage offset, bringing the latest statements gives the adviser cleaner inputs.

What personal goals and life plans will be discussed?

They will be asked what they want life to look like, then the adviser works backwards into numbers. In a first meeting with a financial advisor in Mentone, common goals include buying a home, upgrading, starting a family, reducing money stress, or planning retirement.

They may also discuss timeframes, trade-offs, and which goals matter most if everything cannot be done at once.

How do they assess the household’s current financial position?

They will build a snapshot of net worth and cash flow. A first meeting with a financial advisor in Mentone often covers assets, debts, income sources, regular spending, and any big upcoming costs like school fees or renovations.

This is not about judgment. It is about identifying gaps, pressure points, and what levers can realistically be pulled.

What questions will they ask about income and employment?

They will ask how stable income is and whether it is likely to change. During a first meeting with a financial advisor in Mentone, topics often include salary, bonuses, overtime, casual versus permanent work, parental leave plans, and any side income.

If they run a small business or contract, the adviser may ask about BAS timing, uneven cash flow, and tax set-asides.

How do debts and mortgages get reviewed?

They will look at interest rates, repayment types, and any refinancing options worth modelling later. In a first meeting with a financial advisor in Mentone, they may discuss mortgage structure, offset accounts, credit cards, personal loans, HECS-HELP, and buy now pay later.

They will usually focus on which debts are costing the most and which repayment strategies improve flexibility.

What will be covered about budgeting and cash flow?

They will discuss how money actually moves through the month, not an ideal spreadsheet. A first meeting with a financial advisor in Mentone often explores spending patterns, savings rate, bill cycles, and whether they feel in control.

If cash flow is tight, the adviser may flag quick wins like automating bills, reviewing subscriptions, or setting a realistic buffer before investing.

How is superannuation discussed in the first session?

Super is almost always on the agenda because it is central for Australians. In a first meeting with a financial advisor in Mentone, they may review current funds, investment options, fees, insurance inside super, and whether contributions are being optimised.

They might also explain contribution types like concessional and non-concessional, without locking in recommendations yet.

What investment topics might come up?

They will usually test their comfort with risk and time horizon. In a first meeting with a financial advisor in Mentone, they may discuss basics like diversification, ETFs, managed funds, shares, property, and how investing fits alongside a mortgage.

If they already invest, the adviser may ask why they chose certain assets and whether the portfolio aligns with their goals.

How do they talk about risk tolerance and behaviour?

They will try to understand how they react when markets fall and when bills rise. A first meeting with a financial advisor in Mentone may include questions about past investing experiences, whether they panic-sell, and what level of volatility they can handle.
Financial Advisor

This is less about a questionnaire score and more about working with an Elwood retirement planner to avoid a strategy they will abandon at the first setback.

What insurance and personal protection will be reviewed?

They may discuss whether the household could cope if income stopped. In a first meeting with a financial advisor in Mentone, common topics include life insurance, total and permanent disability, income protection, and trauma cover.

They may also check what cover exists inside super and whether it matches real needs, especially for families with dependants.

How are estate planning and beneficiaries handled?

They will not replace a solicitor, but they will flag gaps that can derail plans. In a first meeting with a financial advisor in Mentone, they may ask about wills, powers of attorney, guardianship for children, and super death benefit nominations.

They might also discuss whether assets are held jointly, in a trust, or in a way that changes what happens if someone dies.

What Centrelink and aged care topics might be raised?

If retirement is near, they may discuss how benefits and assets interact. A first meeting with a financial advisor in Mentone can touch on Age Pension basics, deeming, and how super withdrawals may affect entitlements.

For older clients, they may also outline aged care costs at a high level and suggest specialist follow-up if needed.

How do fees, commissions, and conflicts get explained?

They should explain how they are paid and what it costs before advice is produced. In a first meeting with a financial advisor in Mentone, the adviser may outline fee-for-service models, ongoing advice fees, and any product-related payments that could apply.

They should also explain what is included, what is optional, and how clients can stop an ongoing arrangement.

What regulatory and privacy points will be covered?

They will usually explain their obligations under Australian rules. A first meeting with a financial advisor in Mentone may include how they handle personal data, how advice is documented, and what they must do to act in the client’s best interests.

They may also explain the difference between general information and personal advice, and when formal advice documents are issued.

What does the adviser need to provide after the meeting?

They should outline the next steps and what they will deliver. After a first meeting with a financial advisor in Mentone, this may include a written scope of advice, a list of information needed, and an estimated fee before proceeding.

If they continue, the next stage is often a more detailed fact find, then strategy modelling, then a formal Statement of Advice where required.

What should they ask to check fit and trust?

They should leave confident the adviser understands them and communicates clearly. In a first meeting with a financial advisor in Mentone, useful questions include how they work with similar households, how often they review plans, and what happens when goals change.

They can also ask how the adviser measures success, what assumptions they use, and how they handle market downturns.

How do they prepare to get the most value from the meeting?

They should be clear on goals and honest about money habits, even if it feels uncomfortable. For a first meeting with a financial advisor in Mentone, writing down top priorities, upcoming expenses, and the main financial worries helps keep the session focused.

If they can list accounts and approximate balances, the adviser can spend less time guessing and more time clarifying options.

What outcomes should they expect by the end of the first session?

They should expect a clearer picture of where they stand and what to do next, not a complete plan on the spot. By the end of a first meeting with a financial advisor in Mentone, they should know the proposed scope, estimated costs, and what information is needed.
Financial Advisor

Most importantly, they should feel heard, understand the process, and be able to decide whether to proceed.

FAQs (Frequently Asked Questions)

What is the main purpose of a first meeting with a financial advisor in Mentone?

The main purpose of a first meeting with a financial advisor in Mentone is to gain clarity on your household’s goals and current finances, understand what support you want, and set expectations around fees, advice scope, and next steps. It’s a discovery session designed to map priorities and identify the biggest financial decisions ahead without committing to a long-term plan immediately.

What documents should I bring to my first appointment with a financial advisor in Mentone?

For your first meeting with a financial advisor in Mentone, it’s helpful to bring recent payslips, superannuation statements, a list of debts, and a rough monthly budget. If you have insurance through super, investment accounts, or mortgage offset details, bringing the latest statements will provide cleaner inputs for the adviser.

Which personal goals and life plans are typically discussed during the initial meeting?

During a first meeting with a financial advisor in Mentone, common personal goals discussed include buying or upgrading a home, starting a family, reducing money stress, and planning for retirement. The adviser will explore your desired life outcomes, timeframes, trade-offs, and prioritize which goals matter most if not all can be pursued simultaneously.

How does the financial advisor assess my current household financial position?

In your first appointment with a financial advisor in Mentone, they will build a snapshot of your net worth and cash flow by reviewing assets, debts, income sources, regular spending patterns, and any significant upcoming costs like school fees or renovations. This assessment identifies gaps and pressure points without judgment to determine realistic levers for improvement.

What topics related to income and employment are covered during the initial consultation?

A first meeting with a financial advisor in Mentone will cover income stability including salary details, bonuses, overtime, employment type (casual vs permanent), parental leave plans, side incomes, and if applicable for small business owners or contractors—BAS timing, uneven cash flow patterns, and tax set-asides.

How are fees and potential conflicts of interest explained in the first meeting?

During your first meeting with a financial advisor in Mentone, they will clearly explain how they are paid—including any fees or commissions—and outline what it will cost before producing any advice. They also disclose any potential conflicts of interest upfront to ensure transparency before you decide if they are the right fit for your financial needs.

<script type="application/ld+json">
{
  "@context": "https://schema.org",
  "@type": "BlogPosting",
  "mainEntityOfPage": {
    "@type": "WebPage",
    "@id": "https://tinygreenelephants.com/what-a-first-meeting-with-a-financial-advisor-in-mentone-covers/"
  },
  "headline": "What a First Meeting With a Financial Advisor in Mentone Covers",
  "image": [
    "https://tinygreenelephants.com/wp-content/uploads/2026/09/1-6.jpg",
    "https://tinygreenelephants.com/wp-content/uploads/2026/09/Questions-You-Should-Ask-a-Financial-Planner-840x560-1.jpg",
    "https://tinygreenelephants.com/wp-content/uploads/2026/09/How-much-does-a-financial-adviser-cost-2.jpg"
  ],  
  "author": {
    "@type": "",
    "name": "Kaitlyn Weeks",
    "url": "https://tinygreenelephants.com/author/admin/"
  },  
  "publisher": {
    "@type": "Organization",
    "name": "Tiny Green Elephants Plants",
    "logo": {
      "@type": "ImageObject",
      "url": "https://tinygreenelephants.com/wp-content/uploads/2024/05/cropped-New-logo-12.png"
    }
  },
  "datePublished": ""
}
</script>
Retirement Planner

Retirement Planning in Elwood Looks Different for Renters

Many renters in Elwood enjoy lifestyle and location now, yet worry about rent rises and lease uncertainty later. The goal is to keep the beachside life without letting housing become the budget breaker in retirement.

What makes retirement planning harder for renters in Elwood?

It is harder because housing costs are less predictable and control over tenure is limited. Retirement planning Elwood has to assume rent will change, landlords may sell, and moving might happen at the wrong time.

Elwood’s rental market can be competitive, and even small weekly increases add up over decades. Renters also cannot “pay down” rent the way homeowners pay down a mortgage, so savings and super often need to do more heavy lifting.

Why does housing security matter so much in retirement?

It matters because housing is usually the biggest ongoing expense, and insecurity increases stress and decision pressure. Retirement planning in Elwood should treat housing as a core risk, not a background detail.

If they cannot renew a lease or the rent jumps, it can force a move away from networks, services, and familiar routines. That is especially challenging if health changes or mobility declines later.

How should renters estimate future rent in Elwood?

They should model rent with conservative increases and test a few scenarios. Retirement planning in Elwood works better when renters assume periods of above-inflation rent growth, not just CPI.

A practical approach is to run three projections: steady growth, high growth, and a “forced move” scenario with higher relocation costs. This helps them see how much super and savings need to cover if rent rises faster than expected.

What is the best way for renters to build a retirement budget?

They should separate essentials from lifestyle spending, then stress-test the essentials. Retirement planning in Elwood becomes clearer when renters start with rent, utilities, food, transport, health, and insurance.

From there, they can add discretionary items like dining on Ormond Road, local classes, streaming, and holidays. A strong budget also includes irregular costs such as bond top-ups, removalists, medical gaps, and replacing appliances.

How can renters use superannuation more strategically?

They can focus on contribution consistency, fees, and investment mix that matches time horizon and risk tolerance. Retirement planning in Elwood for renters often benefits from prioritising super growth earlier, because housing is not building equity in the background.

If they have capacity, salary sacrificing or making personal deductible contributions can improve long-term outcomes. They can also review insurance inside super and consolidate accounts where appropriate, as multiple fees can quietly drag results down.

Should renters aim to buy before retirement, or plan to rent for life?

Either path can work, but it needs a deliberate choice rather than a default. Retirement planning in Elwood should compare “buy later” versus “rent for life” using realistic numbers, not wishful assumptions.

Buying might reduce housing uncertainty, but it can also concentrate wealth in one asset and add maintenance, strata, and transaction costs. Renting for life can work if they build a larger investment pool and keep flexibility about suburb, dwelling type, and timing.

What role do investments outside super play for renters?

They provide liquidity and optionality, especially before accessing super or during market downturns. Retirement planning in Elwood often improves when renters build a parallel bucket of investments that can cover bonds, moving costs, and short-term rent spikes.

Common options include high-interest savings, term deposits, managed funds, and ETFs, depending on risk tolerance and time frame. The key is matching the investment to the purpose, not chasing returns for money they may need soon.

How can renters protect themselves against rent rises and lease uncertainty?

They can build buffers, keep documents organised, and reduce decision pressure with a plan B. Retirement planning in Elwood is more resilient when renters maintain an emergency fund that can cover several months of rent and expenses.

Retirement Planner

They can also track comparable rents, renew leases early where possible, and maintain strong rental references. A “plan B” might include using the first meeting with a financial advisor to discuss nearby bayside suburbs, downsizing, or changing dwelling style if the market shifts.

How do Age Pension rules affect renters differently?

Renters may qualify for Rent Assistance and can have different asset test outcomes than homeowners. Retirement planning in Elwood should include a basic check of eligibility, because support can materially change cash flow.

Homeowners can have higher assessable assets before their payment reduces, but renters might receive additional help with rent. Because rules change and personal circumstances vary, many retirees benefit from checking figures with Services Australia guidance or a licensed adviser.

What is downsizing for a renter, and does it still help?

Downsizing for renters usually means reducing rent or choosing a dwelling that lowers ongoing costs. Retirement planning in Elwood can include downsizing choices like moving from a larger apartment to a smaller one, shifting away from premium streets, or choosing a building with lower utilities and better accessibility.

It can also mean simplifying life to reduce transport and medical costs, such as being closer to GPs, pharmacies, and frequent errands. The biggest win is lowering fixed costs, not achieving a particular postcode.

How should renters plan for healthcare and aged care costs?

They should assume rising out-of-pocket health costs and plan for care flexibility. Retirement planning in Elwood works best when renters budget for private health premiums if they want them, plus extras like dental, physio, hearing, and specialist gaps.

Aged care can be complex, and renters may have fewer assets tied up in property, which can affect how they fund care. Early planning focuses on building savings buffers and understanding likely preferences: staying local, accessing home support, or considering residential care.

What practical steps can renters take in their 30s, 40s, and 50s?

They can align contributions, cash buffers, and career income with the reality of renting. Retirement planning in Elwood is often most effective when action starts early, even if they feel behind.

In their 30s, they can prioritise super growth, avoid high debt, and build a habit of investing. In their 40s, they can increase contributions with pay rises and reduce lifestyle creep. In their 50s, they can sharpen their housing plan, boost savings, and map out the transition to retirement income.

How can renters stress-test whether their plan will work?

They can run simple scenarios and look for breaking points. Retirement planning in Elwood should be tested against at least four risks: rent rising faster than income, market downturns near retirement, unexpected health costs, and a forced move.

A useful method is to model a “bad five years” early in retirement, where markets dip and rent rises. If the plan still survives without drastic lifestyle cuts, it is usually more robust.

When should renters get professional advice in Australia?

They should consider advice when decisions have long-term consequences or multiple moving parts. Retirement planning in Elwood may benefit from professional help when they are choosing between buying and renting long term, transitioning to retirement income streams, or managing tax around contributions.

In Australia, only licensed financial advisers can provide personal financial advice. Many people start with general information, then seek personal advice when they need tailored modelling, risk management, or a clearer retirement income strategy.

What does a strong renter-focused retirement plan in Elwood look like?

It looks like stable cash flow, clear housing options, and enough flexibility to adapt. Retirement planning in Elwood for renters typically includes a bigger retirement income target than a homeowner’s plan, because rent continues.

Retirement Planner

A strong plan usually has three layers: a reliable retirement income base (super and/or pension), a liquid buffer for surprises, and a housing strategy with realistic fallback options. If they can fund their essentials under conservative rent assumptions, the lifestyle part becomes far easier to enjoy.

FAQs (Frequently Asked Questions)

What challenges do renters in Elwood face when planning for retirement?

Renters in Elwood encounter challenges such as unpredictable housing costs, limited control over lease tenure, potential rent increases above inflation, and the risk of landlords selling properties. Unlike homeowners, renters cannot build equity through mortgage repayment, so they need stronger cash buffers and more flexible retirement strategies to manage housing expenses effectively.

Why is housing security crucial for retirees who rent in Elwood?

Housing security is vital because housing typically represents the largest ongoing expense in retirement. Insecurity around lease renewals or rent hikes can cause stress and force relocations away from familiar networks and services, which is especially difficult if health or mobility declines. Effective retirement planning treats housing as a core risk to ensure stability and well-being.

How can renters in Elwood estimate future rental costs for retirement planning?

Renters should adopt conservative assumptions by modeling rent with scenarios including steady growth, high growth above inflation, and forced moves with associated relocation costs. This approach helps anticipate how much superannuation and savings must cover potential rent increases and ensures preparedness for varying market conditions.

What strategies should renters use to build a comprehensive retirement budget in Elwood?

Renters should separate essential expenses like rent, utilities, food, transport, health insurance, and medical costs from discretionary spending such as dining out and entertainment. They should also include irregular costs like bond top-ups, moving expenses, and appliance replacements. Stress-testing essentials ensures the budget remains resilient against unexpected financial pressures.

How can renters maximize their superannuation benefits for retirement in Elwood?

Renters can enhance superannuation outcomes by maintaining consistent contributions, minimizing fees, and selecting investment mixes aligned with their risk tolerance and time horizon. Strategies like salary sacrificing or making personal deductible contributions early can accelerate growth since renters do not build home equity. Reviewing insurance within superannuation and consolidating accounts also helps reduce unnecessary fees.

Should renters in Elwood aim to buy property before retirement or plan to rent indefinitely?

Both options are viable but require deliberate evaluation based on realistic financial assessments rather than assumptions. Buying may reduce housing uncertainty but involves maintenance, strata fees, and transaction costs while concentrating wealth in one asset. Renting offers flexibility if accompanied by building a larger investment pool and openness to various suburbs or dwelling types. Retirement planning should compare these paths carefully to align with personal goals.

<script type="application/ld+json">
{
  "@context": "https://schema.org",
  "@type": "BlogPosting",
  "mainEntityOfPage": {
    "@type": "WebPage",
    "@id": "https://tinygreenelephants.com/retirement-planning-in-elwood-looks-different-for-renters/"
  },
  "headline": "Retirement Planning in Elwood Looks Different for Renters",
  "image": [
    "https://tinygreenelephants.com/wp-content/uploads/2026/09/robert-daniele-with-retirement-couple.webp",
    "https://tinygreenelephants.com/wp-content/uploads/2026/09/Australia-How-to-Plan-for-Your-Retirement-1.jpg",
    "https://tinygreenelephants.com/wp-content/uploads/2026/09/618a0509e02dc57532aabc61_Lanham-Financial1.webp"
  ],  
  "author": {
    "@type": "",
    "name": "Kaitlyn Weeks",
    "url": "https://tinygreenelephants.com/author/admin/"
  },  
  "publisher": {
    "@type": "Organization",
    "name": "Tiny Green Elephants Plants",
    "logo": {
      "@type": "ImageObject",
      "url": "https://tinygreenelephants.com/wp-content/uploads/2024/05/cropped-New-logo-12.png"
    }
  },
  "datePublished": ""
}
</script>